Buying your first home in Ontario in 2026 looks very different from buying a first home a few years ago.
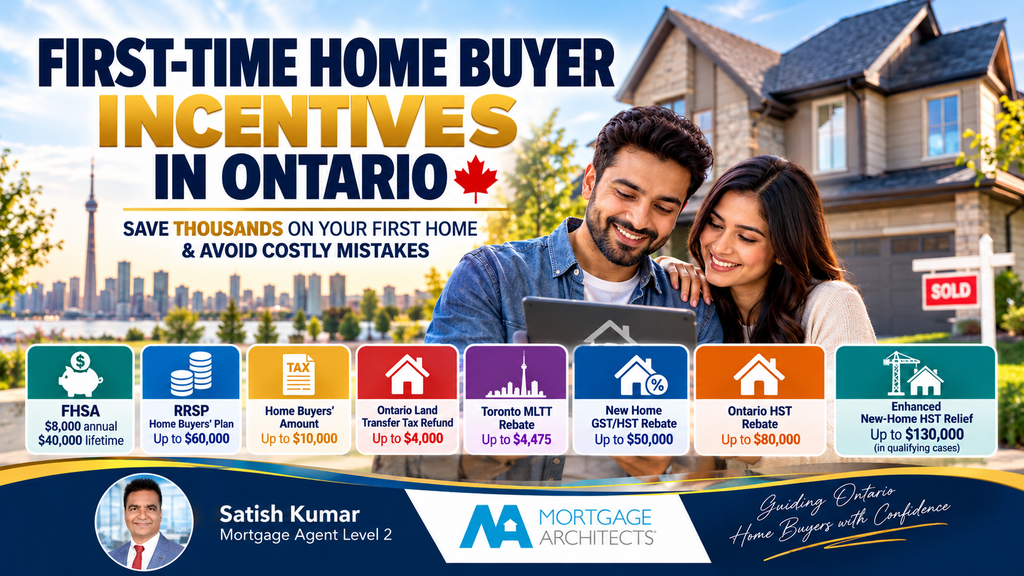
There are still familiar programs such as the First Home Savings Account (FHSA), the RRSP Home Buyers’ Plan (HBP), the federal Home Buyers’ Amount and the Ontario Land Transfer Tax Refund.
But there is also a major new opportunity for eligible buyers purchasing new homes.
The federal First-Time Home Buyers’ GST/HST Rebate can provide up to $50,000 of federal GST/HST relief on eligible new homes. Applications are now open.
Ontario also has a first-time home buyers’ rebate providing up to $80,000 of the provincial portion of HST on eligible new homes.
Separately, Ontario’s temporary expanded HST relief for eligible new homes can provide up to $130,000 in combined federal and provincial HST relief in qualifying circumstances. Importantly, the $130,000 figure should not be treated as a universal first-time-buyer rebate; the eligibility route and timing of the purchase matter.
For resale buyers, the major incentives are different.
You may instead benefit from:
- FHSA tax deductions and qualifying tax-free withdrawals
- RRSP Home Buyers’ Plan withdrawals
- Ontario land transfer tax refund
- Toronto municipal land transfer tax rebate, if purchasing in Toronto
- Federal Home Buyers’ Amount
- Other applicable programs depending on your circumstances
The important lesson is this:
There isn’t one single “first-time home buyer program.” There is a collection of programs with different eligibility rules.
Understanding how they fit together can save you thousands of dollars—and potentially prevent an expensive mistake.
What first-time home buyer incentives are available in Ontario in 2026?
Eligible Ontario first-time buyers may benefit from a combination of:
- First Home Savings Account (FHSA)
- RRSP Home Buyers’ Plan (HBP)
- Federal Home Buyers’ Amount
- Ontario Land Transfer Tax Refund
- Toronto Municipal Land Transfer Tax Rebate, if applicable
- Federal First-Time Home Buyers’ GST/HST Rebate for eligible new homes
- Ontario First-Time Home Buyers’ HST Rebate for eligible new homes
- Ontario’s temporary enhanced HST/new-home affordability measures, where applicable
The programs don’t all have the same eligibility rules, and some are specifically for new construction.
What is the biggest first-time home buyer incentive in Ontario in 2026?
For eligible buyers purchasing qualifying new homes, the federal First-Time Home Buyers’ GST/HST Rebate can provide up to $50,000 in federal GST/HST relief, while Ontario’s first-time home buyers’ rebate can provide up to $80,000 of provincial HST relief. Other Ontario HST measures may also apply depending on the property, purchase date and eligibility.
Table of Contents
1. Who Qualifies as a First-Time Home Buyer?
This is where things become confusing.
There isn’t one universal definition of “first-time home buyer” for every Canadian program.
Different programs can have different tests.
For example, the federal FTHB GST/HST rebate generally requires that you have not lived in a home that you or your spouse/common-law partner owned during the calendar year of purchase or the previous four calendar years. You must also generally be at least 18 and a Canadian citizen or permanent resident.
Ontario’s Land Transfer Tax Refund has a different rule.
Ontario generally requires that you have never owned a home or an interest in a home anywhere in the world, and that your spouse also did not own a home while they were your spouse. Ontario states that you cannot re-qualify for this particular first-time homebuyer refund.
Why does this matter?
You could potentially qualify as a “first-time buyer” under one program but not another.
Never assume that because you qualify for one benefit, you automatically qualify for every first-time-buyer incentive.
2. First Home Savings Account — FHSA
The FHSA is one of the most valuable tools available to Canadians saving for their first home.
The basic structure is attractive:
Contributions can be deductible and qualifying withdrawals for a first home can generally be made tax-free.
The FHSA annual contribution limit is $8,000, with a lifetime contribution limit of $40,000.
Example
Suppose you contribute:
$8,000 per year
for five years.
You could reach:
$40,000
of lifetime contributions, subject to the applicable FHSA rules.
The real advantage is the combination of:
Tax deduction while contributing
plus
Tax-free qualifying withdrawal
when used properly for an eligible first home.
Important FHSA mistake
Opening an FHSA is important because participation room is tied to opening the account.
Simply saying:
“I’ll open one later when I’m ready.”
may mean missing out on valuable contribution room.
3. RRSP Home Buyers’ Plan
The Home Buyers’ Plan allows eligible buyers to withdraw up to $60,000 from their RRSP to buy or build a qualifying home.
And here’s an important 2026 update.
For first HBP withdrawals made between January 1, 2026 and December 31, 2028, the temporary repayment relief means the repayment period begins in the fifth year following the year of the first withdrawal, rather than the second year under the previous rule. Canada
Example
If you make your first qualifying HBP withdrawal in:
2026
your first repayment year would be:
2031
under the current temporary relief.
Can FHSA and HBP be used together?
Yes.
The CRA confirms that an eligible buyer can use an HBP withdrawal and a qualifying FHSA withdrawal for the same home, provided the conditions for each program are met.
That can be a powerful combination.
4. Federal Home Buyers’ Amount
The federal Home Buyers’ Amount provides a non-refundable tax credit.
The CRA currently states that eligible buyers can claim up to $10,000 for a qualifying home acquired in 2025. The resulting tax relief is based on the lowest federal personal income tax rate.
This is different from receiving $10,000 cash.
That’s an important distinction.
Think of it this way:
$10,000 claim amount
does not necessarily mean
$10,000 cash refund.
It is a non-refundable tax credit that reduces federal income tax otherwise payable.
5. Ontario Land Transfer Tax Refund
Ontario first-time home buyers may qualify for a refund of up to:
$4,000
of provincial Land Transfer Tax.
The Ontario government states that qualifying purchasers can receive the maximum $4,000 refund for eligible purchases where the applicable conditions are met.
This can be claimed at registration or, in some circumstances, afterward.
Example
If your Ontario Land Transfer Tax calculation is:
$4,000
and you qualify for the full first-time buyer refund:
Land Transfer Tax after refund = $0
If the tax is higher than $4,000, the refund generally caps at $4,000.
6. Toronto Municipal Land Transfer Tax Rebate
If you’re purchasing a property within the City of Toronto, there’s another potential benefit.
Toronto provides a first-time home buyer rebate of up to:
$4,475
on the Municipal Land Transfer Tax.
This is separate from the Ontario provincial Land Transfer Tax refund.
So an eligible Toronto first-time buyer could potentially receive:
Ontario LTT refund: up to $4,000
plus
Toronto MLTT rebate: up to $4,475
Combined potential:
Up to $8,475
for eligible buyers in Toronto.
This is one reason Toronto buyers should not assume that the provincial Land Transfer Tax refund is the only LTT benefit available.
7. New Federal First-Time Home Buyers’ GST/HST Rebate
This is one of the biggest changes for 2026.
The federal First-Time Home Buyers’ GST/HST Rebate is now available.
Eligible first-time buyers can receive up to:
$50,000
in federal GST or federal HST relief on qualifying new homes.
The program provides:
New home up to $1 million
Potentially 100% of the GST/federal HST component.
New home between $1 million and $1.5 million
The rebate is gradually reduced.
$1.5 million or more
The federal first-time buyer GST/HST rebate is not available.
Important
This is primarily relevant to new or substantially renovated homes, not an ordinary resale home.
8. Ontario First-Time Home Buyers’ HST Rebate
Ontario has also introduced its own first-time home buyers’ rebate.
Eligible Ontario first-time home buyers can receive up to:
$80,000
of the provincial 8% portion of HST on qualifying new homes.
This follows the eligibility conditions associated with the federal first-time home buyer GST/HST rebate.
Potential federal + Ontario relief
For an eligible new home valued at $1 million or less, the federal and Ontario first-time-buyer HST measures can potentially address the full 13% HST, subject to the detailed rules.
That means the theoretical combined HST relief can reach:
$50,000 federal + $80,000 Ontario = up to $130,000
for qualifying circumstances.
The Ontario government also describes up to $130,000 of combined HST relief for eligible new homes.
But there is an important caveat.
Do not assume every first-time buyer automatically receives $130,000.
Property type, purchase agreement date, construction timing, price, primary-residence requirements and the specific rebate route all matter.
9. Ontario’s Enhanced New-Home HST Relief
There is another 2026 development that first-time buyers need to understand.
Ontario’s enhanced new housing rebate can provide up to $80,000 of relief on the provincial portion of HST for qualifying new or substantially renovated homes. The temporary measure generally applies to builder agreements entered into between April 1, 2026 and March 31, 2027, subject to the detailed rules.
The rebate structure includes:
| New Home Value | Potential Ontario ENHR |
|---|---|
| Up to $1 million | Up to $80,000 |
| $1M–$1.5M | $80,000 |
| Above $1.5M–$1.85M | Reduced |
| $1.85M+ | No ENHR; other rebate rules may apply |
Ontario also has the Ontario New Home Affordability Payment (ONHAP).
This is important because it means the 2026 Ontario new-home incentive landscape is more complicated than simply saying:
“First-time buyers get $130,000.”
The actual benefit depends on which federal and provincial programs apply and how they interact.
10. How Do These Programs Work Together?
Here’s a simplified overview.
| Program | Resale Home | New Home | Potential Benefit |
|---|---|---|---|
| FHSA | ✓ | ✓ | $8,000 annual / $40,000 lifetime contribution limit |
| RRSP HBP | ✓ | ✓ | Up to $60,000 |
| Federal Home Buyers’ Amount | ✓ | ✓ | Up to $10,000 claim amount |
| Ontario LTT Refund | ✓ | ✓ | Up to $4,000 |
| Toronto MLTT Rebate | ✓ | ✓ | Up to $4,475 |
| Federal FTHB GST/HST Rebate | ✗ | ✓ | Up to $50,000 |
| Ontario FTHB HST Rebate | ✗ | ✓ | Up to $80,000 |
| Ontario ENHR | ✗ | ✓ | Up to $80,000 provincial HST relief |
| ONHAP | ✗ | ✓* | Up to $50,000, subject to eligibility |
*Eligibility and interaction rules apply.
The biggest takeaway:
The new-home incentives are potentially much larger than the resale-home incentives—but they come with substantially more eligibility conditions.
11. New Home vs Resale Home
This is one of the most important decisions for a first-time buyer.
Resale home
You may benefit from:
- FHSA
- HBP
- Home Buyers’ Amount
- Ontario LTT refund
- Toronto MLTT rebate, if applicable
But the major new GST/HST incentives generally don’t apply because you’re not purchasing a qualifying new home.
New home
You may potentially qualify for:
- FHSA
- HBP
- Home Buyers’ Amount
- Ontario LTT refund
- Toronto MLTT rebate
- Federal FTHB GST/HST rebate
- Ontario FTHB HST rebate
- Ontario enhanced HST relief
- Other applicable new-home measures
This can create a significant difference.
12. Example: $700,000 Resale Home in Ontario
Let’s say a first-time buyer purchases a:
$700,000 resale home
outside Toronto.
They might potentially use:
FHSA
Savings accumulated in an FHSA.
HBP
Up to $60,000 from an RRSP if eligible.
Ontario LTT refund
Up to $4,000.
Home Buyers’ Amount
Potential federal tax relief through the applicable tax credit.
But:
There is no $50,000 federal GST/HST rebate simply because the buyer is a first-time buyer.
Why?
Because the home is a resale property.
13. Example: $700,000 New Home in Ontario
Now change only one variable.
The buyer purchases a qualifying:
$700,000 new home
The buyer may potentially combine qualifying savings/financing tools with applicable new-home HST relief.
For an eligible first-time buyer, the federal and Ontario HST measures can be substantial.
The theoretical HST on $700,000 at 13% is:
$91,000
Under the applicable 2026 relief structure, eligible purchasers of qualifying new homes may be able to recover the applicable federal and provincial HST amounts, subject to the detailed requirements. Ontario describes full 13% HST relief for eligible new homes valued at $1 million or less under its expanded measures.
That can dramatically change the economics of a new-home purchase.
But the buyer should confirm the exact rebate treatment with the builder, CRA and appropriate tax/legal professionals before relying on a rebate in the purchase budget.
14. The $130,000 Number: What Buyers Need to Understand
You’ve probably seen headlines saying:
“First-time buyers can save $130,000.”
There is truth behind the number—but context matters.
The Ontario government describes up to $130,000 in combined HST relief on eligible new homes valued up to $1 million.
However:
It is not a $130,000 cheque.
It is HST relief through specific federal and provincial rebate mechanisms.
It is not available on resale homes.
It is not automatically available to every first-time buyer.
The purchase date matters.
The construction timing matters.
The home value matters.
The type of transaction matters.
Your primary-residence status matters.
This is exactly why buyers should verify the rebate before making an offer based on the assumption that the full amount will be available.
15. Common First-Time Home Buyer Mistakes
Mistake #1: Assuming every first-time buyer gets the same benefits
They don’t.
Different programs use different eligibility tests.
Mistake #2: Treating $130,000 as a universal rebate
It’s not.
The $130,000 figure relates to eligible HST relief on qualifying new homes under the applicable federal and Ontario measures.
Mistake #3: Forgetting Toronto’s municipal tax
If you’re purchasing in Toronto, remember:
Ontario LTT + Toronto MLTT
can both apply.
Mistake #4: Waiting to open an FHSA
Your FHSA room is tied to the account and applicable participation rules.
Opening an account early can be valuable for someone who expects to buy their first home.
Mistake #5: Using every dollar of savings for the down payment
Your down payment isn’t your only closing expense.
Budget for:
- Land transfer tax
- Legal fees
- Appraisal, where applicable
- Home inspection
- Title insurance
- Adjustments
- Moving costs
- Immediate repairs
- Emergency savings
Mistake #6: Buying based on the incentive instead of affordability
A $130,000 incentive does not make an unaffordable home affordable.
Your mortgage payment still has to fit your financial life.
16. First-Time Home Buyer Myth vs Reality
| Myth | Reality |
|---|---|
| First-time buyers get $130,000 cash | The amount relates to specific HST relief on qualifying new homes |
| FHSA gives you $40,000 free money | $40,000 is the lifetime contribution limit |
| HBP is a grant | It is an RRSP withdrawal that generally must be repaid |
| Everyone qualifies for the Ontario LTT refund | Eligibility conditions apply |
| If I owned a home before, I can never qualify for anything | Some federal programs use a four-year lookback rather than lifetime ownership |
| New homes always qualify for the full HST relief | Property, price, dates and eligibility conditions matter |
| Toronto has the same LTT as everywhere else in Ontario | Toronto has its own municipal land transfer tax |
| I should use every incentive available | The best strategy depends on your complete financial situation. |
17. Satish’s Expert Insight
“Don’t shop for a rebate. Shop for the right home.”
As a mortgage professional, I think first-time buyers sometimes get caught up in the incentive headline.
They hear:
“$50,000 GST rebate.”
Or:
“$130,000 HST savings.”
And suddenly a new-build property starts looking much more affordable.
But I would encourage buyers to reverse the order.
First:
Determine what monthly housing payment you can comfortably afford.
Second:
Get properly pre-approved.
Third:
Determine which properties fit your budget.
Fourth:
Then apply the available incentives.
That’s a much safer approach than starting with the incentive and working backward.
A rebate can reduce your upfront cost.
It doesn’t eliminate:
- Mortgage payments
- Property taxes
- Condo fees
- Insurance
- Maintenance
- Utilities
- Closing costs
And it doesn’t protect you from buying more house than you can comfortably afford.
18. First-Time Buyer Checklist
Before opening an FHSA
☐ Confirm eligibility
☐ Open the account
☐ Understand contribution limits
☐ Track contribution room
Before using the HBP
☐ Confirm first-time-buyer eligibility
☐ Confirm RRSP withdrawal amount
☐ Understand repayment obligations
☐ Coordinate with your tax planning
Before making an offer
☐ Get mortgage pre-approved
☐ Establish maximum comfortable purchase price
☐ Calculate closing costs
☐ Determine land transfer tax
☐ Check Toronto MLTT if applicable
☐ Confirm new-home HST rebate eligibility if buying new
Before signing a new-build agreement
☐ Ask the builder how the HST rebate is handled
☐ Confirm whether the rebate is credited at closing
☐ Confirm purchase agreement date eligibility
☐ Confirm occupancy requirements
☐ Review rebate language with your lawyer
☐ Do not assume the full rebate applies without verification
What is the biggest first-time home buyer incentive in Ontario?
For eligible new-home purchasers, the federal and provincial HST measures can provide substantial relief. The federal FTHB GST/HST rebate can provide up to $50,000, while Ontario’s first-time home buyers’ rebate can provide up to $80,000 of the provincial HST portion.
Can I get the $130,000 HST rebate on a resale home?
Generally, no.
The major HST relief discussed in 2026 applies to qualifying new or substantially renovated homes, subject to the program’s specific conditions.
Can I use my FHSA and RRSP Home Buyers’ Plan together?
Yes. CRA confirms that eligible buyers can use qualifying FHSA withdrawals and HBP withdrawals for the same home if they satisfy the requirements of both programs.
How much can I withdraw from my RRSP under the Home Buyers’ Plan?
The current HBP withdrawal limit is $60,000.
How much can I contribute to an FHSA?
The annual limit is generally $8,000, and the lifetime limit is $40,000.
How much is the Ontario first-time home buyer land transfer tax refund?
Eligible first-time purchasers can receive up to $4,000.
How much is the Toronto first-time home buyer rebate?
The City of Toronto provides a municipal land transfer tax rebate of up to $4,475 for eligible first-time purchasers.
Can newcomers qualify for first-time home buyer programs?
It depends on the program.
For example, the federal FTHB GST/HST rebate generally requires the buyer to be a Canadian citizen or permanent resident. Other programs can have different requirements.
Do not assume that immigration status automatically qualifies or disqualifies you from every program.
Can I qualify as a first-time buyer if I owned a home years ago?
Potentially for some federal programs.
For example, the federal FTHB GST/HST rebate uses a current-year/four-previous-calendar-year test related to living in a home owned by you or your spouse/common-law partner.
Ontario’s Land Transfer Tax first-time buyer refund uses a different lifetime ownership test.
This is a perfect example of why program-by-program eligibility matters.
Do first-time home buyer incentives apply to condos?
Potentially.
Many federal new-home programs can apply to qualifying residential condominium units, subject to the specific rules.
Can I get first-time buyer benefits on an investment property?
Generally, many of these programs are designed around a qualifying principal residence.
For example, the federal FTHB GST/HST rebate requires the home to be acquired for use as the buyer’s primary place of residence and includes first-occupancy requirements.
Is the $10,000 Home Buyers’ Amount a $10,000 cash payment?
No.
It is a non-refundable tax credit based on a claim amount of up to $10,000, subject to the applicable tax rules.
20. Your First-Time Home Buyer Action Plan
If you’re planning to buy your first home in Ontario, I recommend following this order.
Step 1 — Establish your budget
Don’t start with the maximum mortgage a lender might approve.
Start with the payment you can comfortably carry.
Step 2 — Open your FHSA if eligible
Don’t unnecessarily delay.
Step 3 — Review your RRSP
Determine whether the HBP could form part of your down payment strategy.
Step 4 — Check your credit
Review your credit report and address problems before applying.
Step 5 — Get mortgage pre-approved
Know your financing range before you start serious house hunting.
Step 6 — Decide between resale and new construction
The incentive landscape can be dramatically different.
Step 7 — Calculate closing costs
Include:
- Land transfer tax
- Legal fees
- Inspection
- Title insurance
- Adjustments
- Moving costs
- Emergency reserve
Step 8 — Verify incentives
Don’t rely solely on a builder’s advertisement or social media post.
Verify eligibility and the applicable rebate rules.
Step 9 — Compare the entire transaction
Look beyond:
Purchase price
and calculate:
Purchase price + HST + rebates + mortgage + closing costs + ongoing carrying costs
Step 10 — Buy within your comfort zone
The best first home is not necessarily the most expensive home you can qualify for.
Final Takeaway
Ontario first-time buyers have access to more home-buying incentives in 2026 than many buyers realize.
The biggest change is the introduction of the new federal first-time home buyer GST/HST rebate, worth up to $50,000 for eligible purchasers of qualifying new homes. Ontario also provides first-time home buyers’ HST relief of up to $80,000, while its temporary expanded new-home HST measures can provide substantial additional relief in qualifying situations.
But don’t let the headline numbers make the decision for you.
A smart first-time buyer should understand:
FHSA + HBP + LTT + GST/HST + mortgage qualification + closing costs + monthly affordability
as one complete financial picture.
The incentive is only valuable if the home itself is affordable.
Buying Your First Home in Ontario?
Before you start booking showings, let’s determine what you can comfortably afford and which first-time buyer programs may apply to your situation.
Satish Kumar
Mortgage Agent Level 2
Mortgage Architects
437 684 3333
info@MortgageWithSatish.com
mortgagewithsatish.com
This article is for general educational purposes only and does not constitute legal, tax, accounting or financial advice. Government programs, eligibility requirements, rebate amounts and lender policies can change. Always verify your eligibility with the applicable government authority, tax professional or lawyer before relying on a rebate or incentive.